The FIRE Number Masterclass
Work out the number that lets you stop working, and exactly which products hold it at every age. Built around Indian tax rules and Indian access restrictions, not an American blog post.
Price goes to ₹199 two days before the class
5,500
Households advised
7 days
Money back
2.5 hrs
Live session
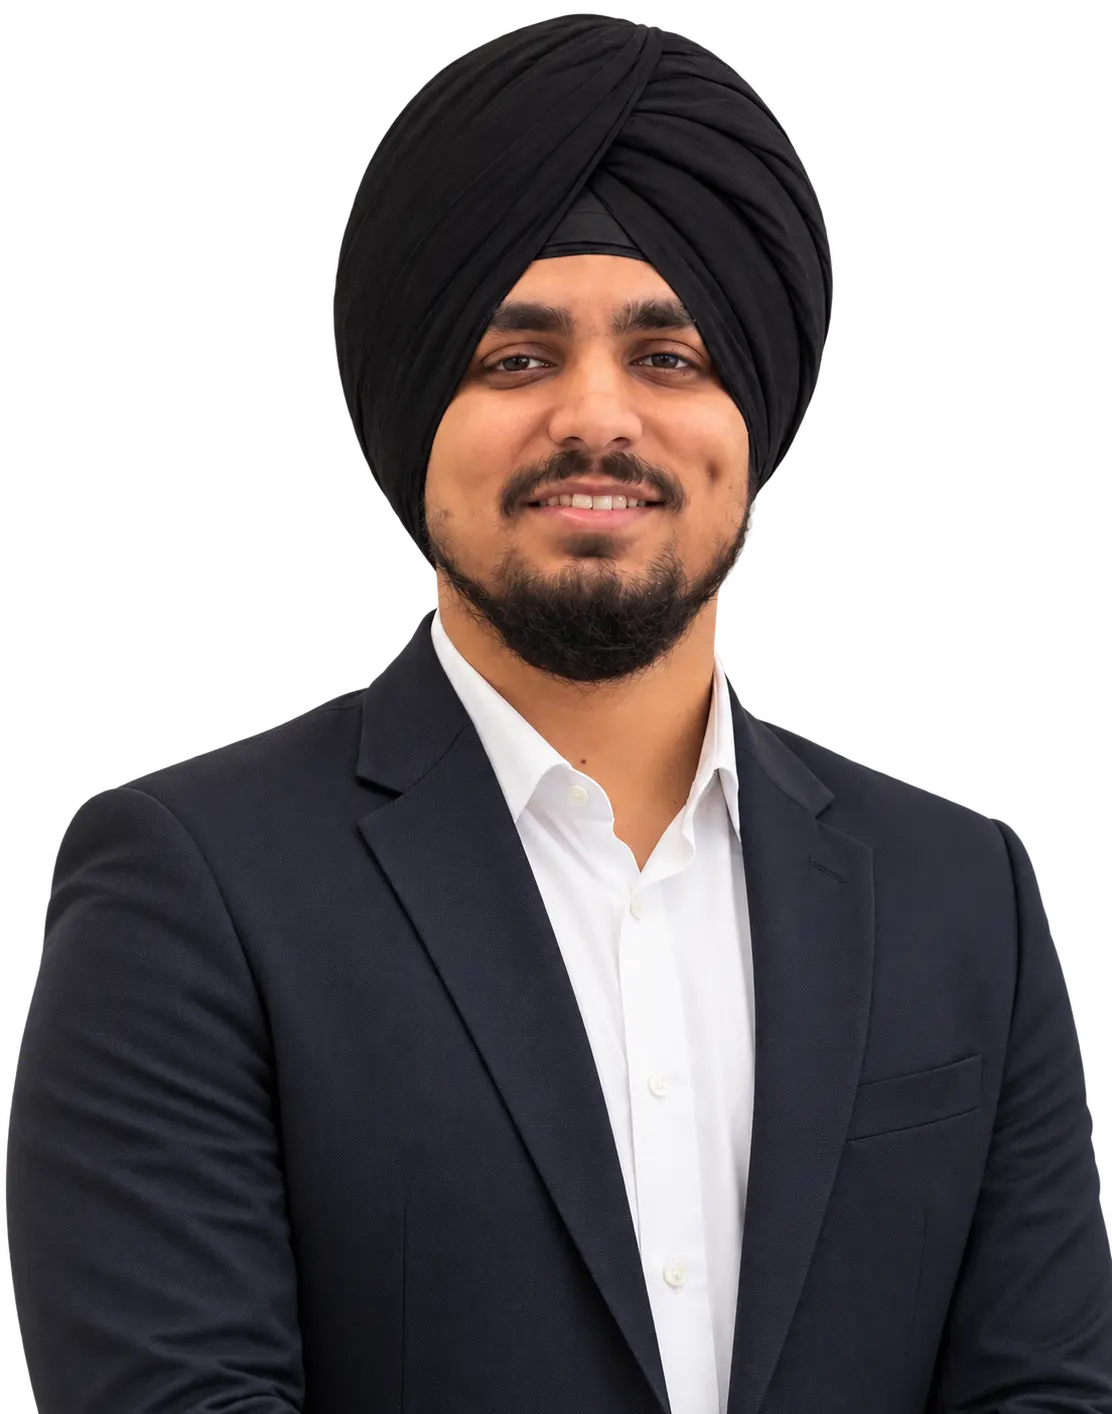
Harman Singh
NISM XA and XB certified
Live next week. Recording for 7 days if you cannot make it.
5,500
Households advised
7 days
Money back
2.5 hrs
Live session
6 worksheets
Tools included
You are not bad with money.
Nobody showed you the arithmetic.
If more than two of these are true, this session was written for you.
You have a corpus in mind, but no idea whether it lasts 25 years or 45.
Most of your retirement money is in EPF, PPF and NPS, and you cannot touch any of it at 40.
You know your monthly SIP, but not what you are allowed to withdraw or what it costs in tax.
Nobody has told you that retiring at 40 needs a different portfolio from retiring at 60.
You are saving hard and still cannot answer the only question that matters: can I stop working earlier?
What is a FIRE number?
The size of corpus at which your investments can pay for your life without your salary. Retirement is not an age. It is that point.
Retirement risk is not just running out of money. It is running out of the right money at the wrong time.
FIRE
The corpus has to last 45 to 50 years, and almost none of it can sit in EPF, PPF or NPS, because you cannot reach those yet.
Early retirement
Ten years to bridge before the locked products open up. Comfortable, but only if the accessible share was planned for.
Traditional retirement
Every Indian retirement product is built for this date. The corpus is larger, and reaching it is the easy part.
What you walk out with
Six specific things, each one usable the same evening.
Calculate your own FIRE number
Built from your spending, your inflation assumption and the number of years the corpus actually has to last. Not a multiple somebody quoted on YouTube.
Split your money into three buckets
What sits in NOW, what funds the FIRE years and what waits until 60. Retiring early is a sequencing problem before it is a saving one.
Match every product to an access age
EPF, PPF, NPS, APY, SCSS, annuity, mutual funds, FD. Which of them you can actually reach at 40, and which stay locked until 60.
Plan the withdrawal, not just the corpus
SWP, interest, pension and rent are taxed differently. Which pot to draw down first so the same corpus lasts years longer.
Use PV, FV and PMT yourself
The three formulas the whole plan rests on, worked on your own numbers so you can redo it any time your spending changes.
Fund the gap between 40 and 60
The twenty years no retirement product in India is designed for, and the bridge that gets you across them.
Minute by minute
The whole run sheet, in the order it happens. No filler, no warm-up.
Retirement is not an age
0 minIt is the point at which your money can support your life without your salary. 40 is FIRE, 50 is early retirement, 60 is traditional. We fix the definition we will use all evening.
The questions nobody asks you
15 minNot how much do I have. How much can I access at 40, how much can keep growing, how much can I withdraw tax-efficiently, and how do I fund my life until 60. That is the whole difference.
Your FIRE number, calculated live
35 minPresent value, future value and PMT on your own spending. Open the calculator with me and fill it in as we go. You leave with your number, not an example.
Why a 40 year retirement breaks the standard plan
1:00A corpus that has to last 40 to 50 years behaves nothing like one that has to last 20. What that does to your withdrawal rate and to how much equity you are allowed to hold.
The retirement income toolkit
1:25All nine products side by side: EPF and PPF, NPS, APY, mutual funds with SWP, FD and debt, SCSS, annuity, rental income and reverse mortgage. Best use, access age and tax treatment for each.
The three buckets
1:55NOW in cash, FD and debt. FIRE years in mutual funds with an SWP and a diversified portfolio. 60 plus in NPS, EPF, PPF, SCSS and annuity. How much goes in each and when you refill them.
The right money at the wrong time
2:15Retirement risk is not just running out of money, it is running out of the right money at the wrong time. A written checklist for your first 90 days, then live questions until they stop.
Your retirement income toolkit
The right product depends entirely on when you need the money. We put all nine on one table in the session and fill in the row that applies to you.
| Product | Best used for | Access | Tax and the key point |
|---|---|---|---|
| EPF and PPF | Safe long-term wealth | Restricted, PPF matures at 15 years | Highly tax-efficient, but not liquid when you need it early |
| NPS | Long-term retirement corpus | Exit restrictions apply | Tax benefits; lump sum and annuity are treated differently |
| APY | A guaranteed minimum pension | Pension starts at 60 | Fixed pension options up to ₹5,000 a month |
| Mutual funds with SWP | FIRE years and flexible income | Highly accessible | Market-linked; a withdrawal is a redemption, so gains may be taxed |
| FD and debt | Near-term income and stability | Generally accessible | Interest is generally taxable at your slab |
| SCSS | Income after 60 | Primarily 60 and above | Regular interest, taxable |
| Annuity | Certainty of income for life | Capital becomes less flexible | Annuity income is generally taxable |
| Rental income | Passive cash flow | Depends on the property | Rental income is taxable and property is illiquid |
| Reverse mortgage | Unlocking home equity | Senior homeowners | Turns home value into cash flow without a normal sale |
EPF and PPF
- Best used for
- Safe long-term wealth
- Access
- Restricted, PPF matures at 15 years
- Tax and the key point
- Highly tax-efficient, but not liquid when you need it early
NPS
- Best used for
- Long-term retirement corpus
- Access
- Exit restrictions apply
- Tax and the key point
- Tax benefits; lump sum and annuity are treated differently
APY
- Best used for
- A guaranteed minimum pension
- Access
- Pension starts at 60
- Tax and the key point
- Fixed pension options up to ₹5,000 a month
Mutual funds with SWP
- Best used for
- FIRE years and flexible income
- Access
- Highly accessible
- Tax and the key point
- Market-linked; a withdrawal is a redemption, so gains may be taxed
FD and debt
- Best used for
- Near-term income and stability
- Access
- Generally accessible
- Tax and the key point
- Interest is generally taxable at your slab
SCSS
- Best used for
- Income after 60
- Access
- Primarily 60 and above
- Tax and the key point
- Regular interest, taxable
Annuity
- Best used for
- Certainty of income for life
- Access
- Capital becomes less flexible
- Tax and the key point
- Annuity income is generally taxable
Rental income
- Best used for
- Passive cash flow
- Access
- Depends on the property
- Tax and the key point
- Rental income is taxable and property is illiquid
Reverse mortgage
- Best used for
- Unlocking home equity
- Access
- Senior homeowners
- Tax and the key point
- Turns home value into cash flow without a normal sale
Which bucket each one belongs in
Retiring early is a sequencing problem before it is a saving one. The money gets sorted by when you need it, not by what it earns.
The next 2 to 3 years
Cash, FD, debt
Money you will spend soon should not be exposed to a bad year.
From the day you stop until 60
Mutual funds with an SWP, a diversified portfolio
The bucket nobody plans. It has to be reachable, because no pension product pays out yet.
60 onwards
NPS, EPF, PPF, SCSS, annuity
Everything the Indian system is actually designed to give you, arriving exactly when it is allowed to.
Retire at 40 and the question stops being how much do I have. It becomes how much can I access at 40, how much can keep growing, how much can I withdraw tax-efficiently, and how do I fund my life until 60.
Taught by Harman Singh
NISM XA and XB certified
Harman has advised 500 households himself and leads a team of eight serving 5,000 more. He teaches with Indian salaries, Indian taxes and Indian inflation, not imported American advice.
- NISM Series XA and XB certified · Investment adviser modules
- Advised 500 households personally
- Leads a team of eight serving 5,000 more
- PGDM in Finance
Everything included
The tools are not a teaser. They are the same models we fill in live, and they are yours after.
Live 2h 30m masterclass
₹999Questions answered live until they run out.
Qubera FIRE Calculator
₹499The corpus model we fill in live, yours to keep. Your FIRE number, the monthly investment it needs and how long the money lasts.
Retirement Income Toolkit
₹399All nine products in one table: what each is best used for, when you can actually access it, and how the income is taxed.
Three Bucket Worksheet
₹299Fill in what covers NOW, what funds the FIRE years and what waits until 60, and see which bucket is short.
PV, FV and PMT sheet
₹299The three formulas with your own numbers already in, so you can rerun the plan whenever your spending changes.
Withdrawal Order Planner
₹199Which pot to draw from first at each age, and what every withdrawal costs you in tax.
Session recording for 7 days
₹199Rewatch anything you missed. The recording opens within 24 hours of the class.
If you bought these separately
₹2,893
You pay today
₹99
That is 97% less than the parts.
Is this for you?
Yes, if you are
- Salaried professionals between 25 and 45 who want a number, not a tip
- Anyone who wants to stop working before 60 and needs to know if it is realistic
- Investors whose retirement money is locked in EPF, PPF and NPS until 60
- People approaching retirement who need an income plan, not another product
- Business owners with irregular income who cannot rely on EPF at all
- Couples planning the FIRE years together for the first time
Skip it, if you want
- Anyone looking for stock tips or intraday calls
- People who want someone else to manage their money for them
- Anyone expecting a get rich quick method
We would rather you did not book than book and want your money back.
The FIRE Number Masterclass
Sat, 26 Sept, 5:00 PM IST · 2h 30m
Only 300 seats left at this price.
- 7 day recording
- All worksheets included
- 7 day money back
If it teaches you nothing, it is free
If you finish the class and feel you learned nothing new, write to harman@qubera.club within 7 days. We refund the full amount, no form and no questions. We can make that promise because almost nobody takes it.
Questions people ask
What is a FIRE number?
It is the size of corpus at which your investments can pay for your life without your salary. Retirement is not an age, it is that point. Reaching it around 40 is usually called FIRE, around 50 early retirement, and around 60 the traditional kind. The arithmetic is the same for all three, but the earlier you stop the longer the money has to last, which is why a FIRE number is so much larger than people expect.
I already have EPF, PPF and NPS. Is that not my retirement plan?
It is most of a plan for retiring at 60. It is almost none of a plan for retiring at 45, because all three are built around 60 and you cannot freely draw from any of them before then. If you stop at 45 you have fifteen years to fund first. A large part of this session is working out how much of your money has to sit somewhere you can actually reach.
Do I need to be good at maths?
No. Three formulas do the whole job, present value, future value and PMT, and we fill them in together on your numbers rather than deriving anything. If you can use a calculator you can follow every step.
How do I join the masterclass?
You get a joining link by email and WhatsApp as soon as you book, again 24 hours before, and once more an hour before we start. The link works on a phone and on a laptop. Nothing to install.
What if I cannot attend live?
Book anyway. The recording opens within 24 hours and stays available for 7 days, along with every worksheet. The live session is better because you can ask questions, but you will not lose the material.
Which language is the class in?
Simple English, with Hindi used freely wherever it explains something faster. No finance jargon without a plain explanation first.
I know nothing about investing. Is this too advanced?
It is built for someone starting from zero. We begin with what a FIRE number even means, and every tool is filled in live so you are never left looking at a blank spreadsheet.
I already invest. Will I learn anything new?
The parts most existing investors take away are the bridge to 60, the withdrawal order across nine products, and seeing their own FIRE number in the rupees of the year they actually stop rather than today's. If none of that is new to you, take the refund. That is why it exists.
Is this investment advice?
No. This is education. We show you the method, the maths and the tools. We do not recommend specific securities, and we do not sell you a product at the end. For advice on your personal situation, speak to a SEBI registered investment adviser.
What is the refund policy?
If the class did not teach you anything new, write to harman@qubera.club within 7 days and we refund the full amount. No form, no questions.
Will you try to sell me something in the class?
There is no pitch at the end. We mention our other masterclasses once, briefly, and then get back to your questions.
Still deciding?
You read the whole page, which means the question is not whether this is useful. Come and see it for yourself. If it is not worth what you paid, tell us and we send it back.
900 rupees off, for now
Harman Singh